Before converting a downtown building to lofts in a tertiary market, test the spread between all-in basis and finished value. Price the acquisition per door, get local contractor estimates for the conversion, add soft and carrying costs, and compare the total with real sales or rent comps, not listings. Then check parking, absorption, infrastructure, historic tax credit eligibility and Opportunity Zone status before you commit.
Urban loft development can create compelling returns in tertiary and secondary markets — particularly when developers acquire older downtown buildings at a significant discount to the cost of stabilized residential product. But a cheap historic building is not automatically a good development opportunity. Here is the complete framework for evaluating a conversion before you buy: acquisition basis per door, real conversion costs, achievable rents and condo prices, absorption, parking, floorplates, historic tax credits, Opportunity Zones, infrastructure red flags, and a 9-step feasibility test — anchored by real sales and permitted-cost benchmarks from Kingsport, Tennessee.
Direct Answer
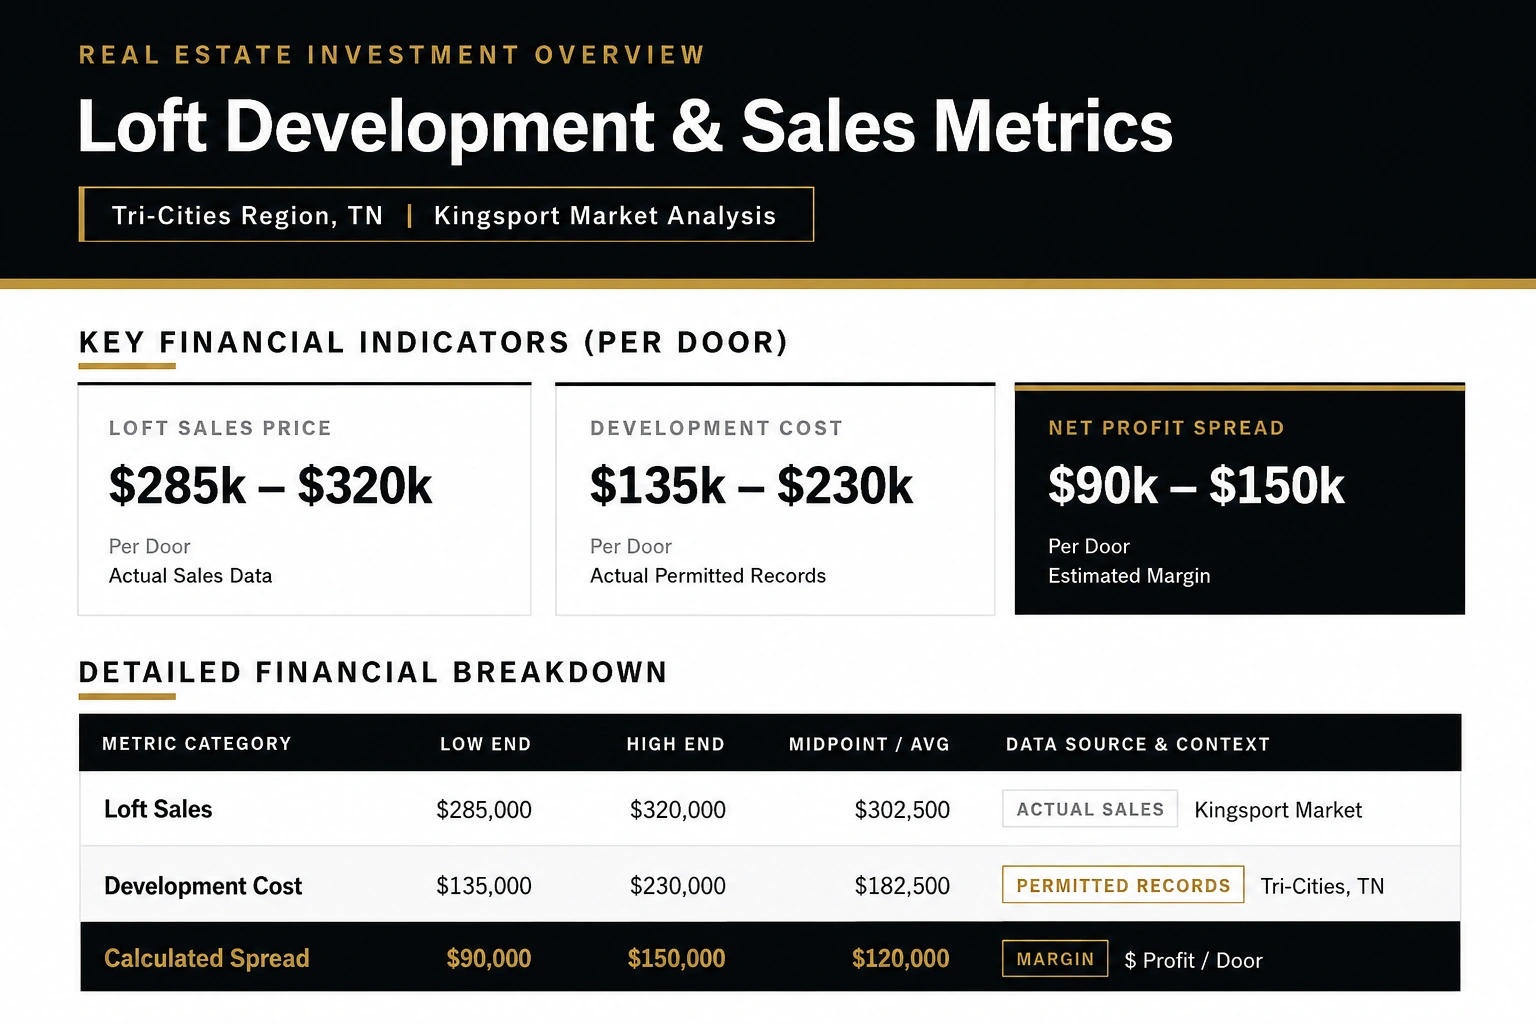
Urban loft developments in tertiary markets can yield healthy gross profit margins when total development costs stay below roughly $182,500 per door. Market data from regional centers like Kingsport, TN indicates completed unit sales averaging $285,000 to $320,000 per unit (about a $302,500 midpoint), against permitted development-cost benchmarks of $135,000 to $230,000 per unit — an expected gross profit spread of roughly $90,000 to $150,000 per door. Those are local benchmarks, not transferable assumptions: the analysis every developer must run is what does the finished product actually sell for here, and how far below that number can we deliver it?
| Metric Category | Low End | Midpoint / Avg | High End | Key Context / Data Source |
|---|---|---|---|---|
| Loft Sales Price (per unit) | $285,000 | $302,500 | $320,000 | Actual completed sales — Kingsport, TN |
| Development Cost (per unit) | $135,000 | $182,500 | $230,000 | Permitted municipal records — Tri-Cities, TN region |
| Calculated Profit Spread | $90,000 | $120,000 | $150,000 | Estimated gross margin per door |
Are urban loft developments profitable in tertiary markets?
They can be, but profitability depends heavily on the spread between total development basis and achievable stabilized value or unit sale price. In larger metropolitan areas, developers may pay substantial premiums for downtown buildings because residential demand is already established. Tertiary markets can offer a different equation:
However, the lower acquisition cost is only valuable if the market supports the finished units. A developer should therefore work backward from the exit rather than forward from the purchase price. For a condominium strategy:
For rental lofts, the analysis should instead work backward from achievable NOI and an appropriate stabilized exit cap rate. Developing urban lofts in tertiary markets presents a unique risk-reward dynamic: construction costs mirror secondary markets, but top-line exit pricing relies heavily on localized demand depth.
What should a developer analyze before buying a building for loft conversion?
Before buying a building for loft conversion, check the acquisition basis and cost per developable unit against real loft sales, rents and absorption. Then inspect what makes conversion possible or expensive: parking, floorplate depth, windows, ceiling heights, elevators, fire and life safety, utilities, structure, environmental issues, historic status, zoning and available incentives.
Before acquiring a potential conversion property — an old office, warehouse, bank, department store, or mixed-use building — developers should generally investigate: acquisition basis, cost per developable residential unit, comparable loft and condominium sales, comparable apartment rents, unit absorption, parking availability, floorplate and building depth, window locations, ceiling heights, elevator requirements, fire and life-safety requirements, plumbing and utility capacity, structural condition, environmental conditions, historic designation or eligibility, local zoning, tax credits and redevelopment incentives, construction financing availability, population and employment trends, and the depth of the eventual renter or buyer pool.
The mistake is underwriting the project primarily because the building appears inexpensive.
The building isn't cheap if it costs too much to make it usable.
What is the right acquisition basis for an urban loft conversion?
There is no universal price per square foot that makes a loft development viable. Developers should instead calculate their all-in basis per sellable or rentable unit. Suppose a developer buys a 25,000-square-foot downtown building for $1.25 million — a headline basis of $50 per square foot. That sounds inexpensive. But if only 15,000 square feet can economically become residential space and the project produces 15 units, the acquisition cost alone represents roughly $83,333 per residential unit — before architecture, construction, financing, contingency, common areas and developer overhead.
What will my all-in basis per door be relative to the demonstrated value per door? That is ultimately the spread that matters.
How much does it cost to convert an older building into urban lofts?
There is no reliable national per-unit number because adaptive reuse projects vary enormously. Major cost variables include structural condition, roof, electrical service, HVAC, plumbing, elevators, sprinklers, fire separation, windows, façade work, environmental remediation, accessibility requirements, historic preservation requirements, unit finish level, local labor costs, and the efficiency of the existing floorplate.
Developers should be particularly careful with beautiful buildings that have experienced decades of deferred maintenance. Exposed brick and timber may create tremendous residential character. They do not compensate for a failed roof, obsolete electrical system or a floorplate that cannot efficiently accommodate residential units.
Cost overruns compress margins fast: controlling development costs below $182,500 per unit maintains a $120,000+ spread per door at Kingsport-level pricing. If adaptive-reuse costs surge to $230,000 per door, margins compress to roughly $90,000 per door even at top-of-market pricing ($320,000).
How do you determine whether a tertiary market can support luxury loft pricing?
Start with transactions — not asking prices. Identify what buyers actually paid for comparable finished units, then analyze those sales by price per unit, price per square foot, unit size, bedrooms, parking, finish quality, floor, views, building amenities, and date of sale.
Case study: Kingsport, Tennessee
Recent market work compiled for downtown loft development found actual loft sales in approximately the $285,000–$320,000 per-unit range, with a midpoint around $302,500. The same analysis identified permitted development-cost benchmarks across the broader Tri-Cities market ranging from approximately $135,000–$230,000 per unit. Those figures are not assumptions to apply to other tertiary markets — they illustrate the type of local evidence a developer should obtain before underwriting a conversion, and the underlying report specifically cautions that its figures are general market benchmarks subject to project-specific verification.
That's the correct way to approach tertiary markets: use local evidence instead of national assumptions.
What makes an urban loft command a premium in a smaller market?
Not every apartment inside an old building is a loft. Authenticity can be part of the value proposition. Achieving top-tier pricing ($320,000+ per door) requires preserving authentic architectural elements rather than modern drywall-box finishes: open-plan great rooms paired with island kitchens; restored original exterior brick, heavy timber framing, and structural elements; restored large window openings providing downtown or mountain-ridge views; and minimum 10 ft. ceiling clearances featuring exposed mechanical ductwork.
In a tertiary market the project may not be competing against another historic loft building — it may be competing against a suburban apartment, single-family home or newer townhome. The developer needs to answer:
Why would someone choose this product instead?
How important is parking for a downtown loft development?
Potentially very important. A municipality might permit a residential conversion with little or no dedicated parking — the buyer may still expect convenient parking. Those are two different questions. Investigate dedicated on-site parking, municipal garages, leased parking, overnight parking rights, assigned spaces, street parking, EV charging, guest parking, and the walking distance between parking and the residence. For condominium projects, the ability to provide or contractually secure parking may materially influence both pricing and absorption.
Should a developer build apartments or for-sale loft condominiums?
This should be determined by the market and capital structure rather than personal preference. Rental lofts make sense when market rents support the development basis, long-term residential demand is strong, financing favors rental product, and the developer wants to hold. For-sale lofts make sense when comparable condominium sales establish substantially more value per unit than rental capitalization supports and there is sufficient depth among owner-occupant or second-home buyers. There is also a third possibility: a mixed strategy — retail or restaurant space on the ground floor with residential above, plus rooftop, basement, office or hospitality uses creating additional revenue.
The highest-value redevelopment isn't necessarily 100% residential.
How many loft units should a developer put in the building?
The answer should not simply be “as many as possible.” Unit count affects construction cost, average unit size, achievable pricing, plumbing, parking, common-area efficiency, buyer demographics, and absorption. If a market has demonstrated demand for $300,000 two-bedroom lofts, doubling the unit count with micro-units does not necessarily improve the economics. Test multiple configurations — e.g., Scenario A: 12 large premium lofts; Scenario B: 18 conventional one- and two-bedroom units; Scenario C: 24 smaller rental units — and compare development cost, revenue, absorption and financing under each.
The objective is not maximum density. It's maximum risk-adjusted value.
How do you estimate demand for lofts when there are very few comparable properties?
This is one of the biggest challenges in tertiary-market development. Lack of comparable product can mean an unmet market opportunity — or not enough demand to support the product. Look to additional indicators: downtown residential occupancy, competing apartment occupancy, condominium sales velocity, employer base, household incomes, regional trade-area population, major hospitals and universities, corporate relocation activity, tourism, retiree migration, second-home demand, downtown restaurants and entertainment, walkability, and announced downtown investment. Tertiary markets should often be analyzed regionally rather than strictly by municipal population.
How much absorption risk exists in a small-market condominium development?
A project can be profitable on paper and still experience problems if it takes three years to sell the units. 20 units × $300,000 = $6 million of gross sellout value — but that number alone says little about risk. If the market absorbs two units per month, the project behaves very differently than if it absorbs one unit every two months. Slow absorption increases interest expense, taxes, insurance, HOA exposure, marketing costs, maintenance, and the developer's capital duration.
Developers should underwrite time as aggressively as they underwrite price.
Evaluating a Downtown Building?
Carson Jones is a licensed commercial real estate advisor and business broker with eXp Commercial. Get a second set of eyes on the basis, the comps, and the exit before you go hard.
Are historic tax credits available for urban loft developments?
Potentially. Historic buildings may qualify for federal and/or state historic rehabilitation incentives depending on the building, jurisdiction, ownership structure and planned rehabilitation — but don't assume a building qualifies simply because it is old. Historic programs can impose rehabilitation standards affecting windows, façades, interior features, materials, mechanical placement, and construction methods, so evaluate the economic benefit alongside the cost and design constraints with qualified historic preservation, tax and legal professionals.
Stackable with Opportunity Zones? Yes — developers routinely combine Federal/State Historic Tax Credits (HTC) with Qualified Opportunity Funds to subsidize 20–25% of qualified rehabilitation expenses (QRE) while insulating equity gains from future taxation.
Can Opportunity Zones improve the economics of a loft development?
Potentially, if the property is located in a qualifying Opportunity Zone and the structure satisfies the applicable federal requirements. Rolling capital gains (from property, stock, crypto, or business sales) into a Qualified Opportunity Fund (QOF) allows developers or equity partners to defer original taxes while securing 100% tax-free growth on the new investment after a 10-year hold. Example: reinvesting a $1,000,000 gain into a QOF that grows to $2,500,000 over 10 years excludes the entire $1,500,000 of appreciation from federal tax. Note: real estate flipping generates ordinary income and does not qualify; eligible funds require actual capital gains.
A weak real estate project does not become a good development simply because it sits inside an Opportunity Zone. The real estate still has to work.
What infrastructure issues kill urban loft conversions?
The deal killers usually hide behind the walls: inadequate electrical capacity, water and sewer service that cannot handle the unit count, no efficient path for individual HVAC, new sprinkler requirements, residential egress, an unusable elevator, and windows that cannot meet light and ventilation codes. Investigate each of these systems before closing, not after demolition starts.
Some of the biggest redevelopment problems are hidden behind the walls. Before closing, investigate at minimum:
| System | The Question That Kills Deals |
|---|---|
| Electrical | Is there enough capacity for modern residential loads? |
| Water & sewer | Can existing service accommodate the proposed unit count? |
| HVAC | Can individual systems be installed efficiently? |
| Fire protection | Does the building require new sprinkler infrastructure? |
| Egress | Can residential code requirements be satisfied? |
| Elevators | Is an existing elevator reusable, or will a new system be required? |
| Windows | Can existing openings satisfy light, ventilation and egress requirements? |
| Structure | Can floors support the proposed residential use and rooftop amenities? |
| Environmental | Are asbestos, lead, underground tanks or other conditions present? |
These issues can erase what initially appeared to be a large acquisition discount.
What should a developer look for in the building's floorplate?
Floorplate efficiency can determine whether an adaptive reuse project works. The ideal historic loft candidate often has abundant exterior windows, manageable building depth, logical corridor placement, adequate ceiling height, usable column spacing, existing vertical circulation, accessible plumbing routes, and minimal unusable interior space. A deep historic building with few windows may be inexpensive for a reason — residential units require light.
You cannot solve every floorplate problem with better finishes.
How large should the contingency be on an adaptive reuse project?
Typically larger than on predictable new construction. Existing buildings contain unknown conditions that even extensive due diligence cannot fully expose before demolition begins. Stress test in sequence: What happens if construction costs increase 10%? Then: what happens if sales prices decline 10%? And finally: what happens if both occur while absorption takes six months longer than expected? If the project still produces an acceptable return, there may be a meaningful margin of safety. If it only works in the best case, the acquisition basis may be too high.
What is the biggest mistake developers make in tertiary markets?
Assuming low acquisition price equals low risk. It doesn't. A $40-per-square-foot historic building can be substantially riskier than a $100-per-square-foot building if the cheaper property requires major structural, mechanical or environmental work. The opportunity usually comes from basis relative to achievable value, not basis alone. Four questions eliminate a surprising number of bad deals: What am I buying it for? What will it cost to create the finished product? What has that finished product actually sold or rented for? How long will it take the market to absorb it?
What numbers should developers know before making an offer?
Know the acquisition price per square foot and per unit, the development cost per unit, and the all-in basis per unit, then compare them with what the market supports: rent per unit, actual sale prices per unit and per square foot, gross sellout and stabilized NOI. If all-in basis is not well below finished value, walk away.
| Metric | Developer Question |
|---|---|
| Acquisition PSF | What am I paying for the existing building? |
| Acquisition Cost / Unit | How much purchase basis is allocated to each proposed door? |
| Development Cost / Unit | What will the conversion actually cost? |
| All-In Basis / Unit | What is my true cost after acquisition, construction and soft costs? |
| Rent / Unit | What does the rental market support? |
| Sale Price / Unit | What have comparable finished units actually sold for? |
| Sale Price / SF | Does pricing make sense relative to alternatives? |
| Gross Sellout | What is total projected revenue? |
| Stabilized NOI | What does the project generate if held? |
| Exit Value | What might the stabilized rental project be worth? |
| Absorption | How long will lease-up or sellout take? |
| Contingency | How much room exists for surprises? |
| Developer Margin | Is the return sufficient for adaptive-reuse risk? |
How do you run a quick feasibility test on an urban loft development?
Before paying for architecture and engineering, determine realistic finished value from actual sales or rent comps, estimate achievable unit count with an experienced professional, and divide acquisition and predevelopment costs across those units. Add local contractor construction estimates plus soft and carrying costs, then confirm the spread between all-in basis and finished value covers the risk.
Before spending significant money on architecture and engineering, run this first-pass screen:
- Determine realistic finished value. Use actual sales or rental comps rather than optimistic listings.
- Estimate achievable unit count. Have an architect or experienced development professional review the floorplate, windows, circulation and code constraints.
- Establish acquisition basis per door. Divide acquisition and major predevelopment costs across the realistic unit count.
- Estimate construction costs. Use local contractor input rather than generic national figures.
- Add soft costs and carrying costs. Architecture, engineering, permits, financing, taxes, insurance, marketing and sales costs.
- Add contingency. Adaptive reuse deserves it.
- Compare total basis against conservative exit value. Then stress test both sides.
- Evaluate absorption. How long will it actually take to rent or sell the finished units?
- Investigate incentives. Only after the underlying economics work should tax credits, grants or Opportunity Zones be layered in.
Frequently Asked Questions About Urban Loft Development
Is urban loft development viable in a city with fewer than 100,000 residents?
Potentially. Municipal population alone is not sufficient to determine demand. Developers should analyze the broader trade area, employment base, incomes, migration, tourism, healthcare, universities, downtown activity and comparable residential performance.
What is a good profit margin for a loft development?
There is no universal target. Required returns vary based on leverage, construction risk, project duration, presales, market depth and developer strategy. Adaptive reuse generally needs enough margin to compensate investors for greater construction uncertainty.
Are historic buildings cheaper to convert than building new apartments?
Sometimes, but not necessarily. A low acquisition basis can be offset by structural repairs, elevators, windows, environmental remediation, mechanical systems and historic requirements.
Do loft developments need dedicated parking?
That depends on zoning and the target customer, but developers should distinguish between what zoning requires and what residents actually demand.
Are urban lofts better as rentals or condominiums?
It depends on the relationship between achievable rents, cap rates, condominium pricing and absorption. Developers should model both exits before committing to a strategy.
What makes a building a good loft-conversion candidate?
Strong candidates typically combine an attractive acquisition basis with large windows, high ceilings, efficient floorplates, structural character, manageable utility upgrades, parking access and demonstrated residential demand.
Should tax credits make the deal work?
Ideally, no. Incentives should improve an already defensible real estate investment rather than rescue a project whose underlying development economics do not work.
Are historic preservation tax credits stackable with Opportunity Zone funds?
Yes. Developers routinely combine Federal/State Historic Tax Credits (HTC) with Qualified Opportunity Funds to subsidize 20–25% of qualified rehabilitation expenses (QRE) while insulating equity gains from future taxation.
What is the primary risk factor when converting historic downtown buildings?
Environmental remediation (lead, asbestos), structural timber repair, and upgrading utility infrastructure (sprinkler systems, water lines) represent the most frequent sources of cost creep from Entry Tier ($135k) into Upper Tier ($230k) cost categories.
Do office-to-residential conversion numbers actually work outside the big cities?
They work in a narrow band and fail everywhere else. The deals that pencil share three things: an acquisition basis under roughly $30 a foot, a floor plate shallow enough that every unit gets real windows, and either historic credits or an Opportunity Zone to close the last gap. Big-city Class A towers usually fail because the basis is too high and the floor plate too deep. A four-story 1920s building on a downtown square in a market of 40,000 can work because you bought it near land value. Run the exit rent first. If achievable rent will not carry all-in cost per door, design does not fix it.
What does a loft conversion actually cost per square foot?
In tertiary markets, budget $140 to $220 a foot for a full gut conversion of a masonry building, which usually lands between $150,000 and $250,000 per door at typical loft sizes. The spread comes from what the building already has. An existing sprinkler riser, a sound roof and usable stairs move you toward the low end. A new elevator, structural repair, full mechanical and window replacement move you to the high end quickly. Get a contractor walkthrough before you go hard on the purchase. Budgets built off a spreadsheet template are how these projects lose money.
What life safety and accessibility upgrades get triggered when I change a building from commercial to residential?
Changing occupancy opens the whole code, not only the parts you touch. Expect a full sprinkler system, rated corridors and stair enclosures, two means of egress, fire alarm, energy code compliance on the envelope, and accessibility on the ground floor plus an accessible route. Historic status can earn relief through the existing building code, but that gets negotiated with the building official, not assumed. Get your architect and the code official inside the building together before you sign a purchase contract, because these items are the difference between $150 a foot and $220.
How do I finance a loft conversion when the banks do not want the deal?
Local banks fund these, national ones generally do not, and they underwrite the sponsor as much as the project. Expect 30 to 40 percent equity, a personal guarantee, and a lender who wants to see your general contractor history on similar buildings. Historic credit equity and an Opportunity Zone fund can fill part of the stack, but credit equity funds at completion, so you still need bridge capital to carry it. Bring a real budget, a signed GC contract, and rent comps from executed leases rather than listings.
Do I need an elevator, and what does adding one cost?
If you are building units above the first floor, plan on one. Code may not force it in a small walk-up, but the market does, and it drives which tenant you attract and what rent you hold. In a tertiary market a new hydraulic elevator in an existing building runs roughly $150,000 to $250,000 installed once you account for the shaft, pit, machine room and structural work, plus several thousand a year in maintenance and inspection. Decide early, because the shaft location dictates unit layout on every floor.
What is the bottom line on urban loft development in tertiary markets?
It is a basis-versus-value strategy. The question is not how cheaply you can buy an old building, but how far below the finished product's value you can create your all-in basis. Kingsport, where finished lofts sold for roughly $285,000 to $320,000 per door, shows why these markets deserve a closer look.
Urban loft development in tertiary markets is ultimately a basis-versus-value strategy. The question isn't “How cheap can I buy this old building?” The better question is:
“How far below the value of the finished product can I create my all-in basis — and is that spread large enough to compensate me for construction, financing and absorption risk?”
Kingsport, Tennessee provides one example of why developers should investigate these markets rather than dismissing them based solely on population: actual finished loft sales between approximately $285,000 and $320,000 per door against permitted development-cost benchmarks of $135,000 to $230,000 per door. Those numbers don't prove that every building in Kingsport works, much less that the economics transfer to another city. They demonstrate the due-diligence question worth asking in every tertiary market:
What does the finished product sell for — and how far below that number can we deliver it? That is where the development opportunity begins.
For the expanded developer guide — including the full 20-point pre-acquisition checklist and design-driver breakdown — see the companion resource at Carson's Corner: Urban Loft Development in Tertiary Markets.
Educational content only — not legal, tax, engineering, or investment advice. Sales prices, development costs, incentive rules and market benchmarks referenced here (including the Kingsport / Tri-Cities figures) are general market data subject to project-specific verification and change over time. Consult qualified legal, tax, preservation and construction professionals before acting.
Adaptive Reuse Questions Small-Market Developers Ask
These are the questions owners, investors, and first-time developers ask most often about converting older downtown and small-town buildings into lofts and apartments. They cover feasibility, zoning, building systems, hotel conversions, historic tax credits, downtown grants, and deal structure.
Is a small-town conversion feasible?
Is it feasible to convert a small-town commercial building into apartments?
Often yes, if the building has windows on enough sides, a workable floor depth, a sound structure, and zoning that allows residential use. Upper floors of two- and three-story downtown buildings are frequently the easiest candidates. Feasibility then comes down to whether conversion cost plus purchase price can be supported by local rents, which in smaller markets usually requires a low acquisition basis and help from tax credits or grants.
Can a former small-town movie theater be converted into apartments?
It is possible but usually difficult. Theaters have large, windowless volumes, sloped floors, and few exterior openings, so creating units with natural light and code-compliant egress can require cutting new windows, adding floors, or building light wells. They often work better as mixed-use or event space with apartments in a front section. Expect high structural and design costs, and get an architect's opinion before buying.
Would a small-town building costing about $330,000 all-in and earning about $23,000 a year in rent attract investors?
Probably not at that price as a pure investment. $23,000 on $330,000 is about a 7% gross yield, and after taxes, insurance, maintenance, vacancy, and management, the net return is likely closer to 4% to 5%, below what most small-market investors require. The building becomes more attractive with higher rents, a lower basis, grants or tax credits, or a buyer who also uses part of the space.
Is a small-town mixed-use building attractive to a buyer who lives upstairs and runs the ground-floor business?
Yes, this live-work buyer is often the best match for small-town mixed-use buildings. An owner-occupant values the combined savings on housing and business rent, and may qualify for owner-occupied financing such as SBA loans if the business uses most of the building. Market the property to restaurant operators, retailers, and professionals who would benefit from living above their business.
Should an owner walk away, cut the price, or reposition a small-town conversion property that will not sell?
First figure out why it is not selling. If buyers object to price, a reduction to a level that supports a reasonable return is often the fastest fix. If they object to risk, reduce it by getting plans, permits, cost estimates, grant commitments, or a lease signed. Offering seller financing can widen the buyer pool. Walk away only if carrying costs exceed the likely recovery.
When choosing a building to convert, do amenities matter more than location?
Location matters more. Buyers and renters choose walkable downtowns, proximity to restaurants and jobs, and a safe, active street, and you cannot add those to a building. Amenities help differentiate a project once the location works, such as exposed brick, high ceilings, rooftop space, storage, and in-unit laundry. In small markets, a few distinctive features usually beat an expensive amenity package.
Zoning and parking
Can you convert a mixed-use or commercial building to all apartments without rezoning?
Sometimes. Many downtown and central business district zones allow residential uses, sometimes on upper floors only, while others require ground-floor commercial frontage. If residential is not permitted, you may need a rezoning, a special use permit, or a variance. Check the zoning code, ask the planning department, and confirm parking and density rules before buying.
What is the biggest hurdle in converting a building to housing: zoning or capital costs?
Capital costs are usually the bigger hurdle, though zoning can kill a project outright. Older buildings need new plumbing, electrical, fire protection, and egress, and costs in smaller markets are not much lower than in big cities while rents are. Many cities now encourage downtown housing, so zoning approvals may be easier than the financing gap. Get both a zoning review and a cost estimate early.
How do developers weigh giving up site area for parking versus more units?
Compare the value each parking space adds with the value of the units or space it replaces. In small markets, renters often expect parking, so some on-site or nearby leased parking may be needed to lease up. But surface parking on a small downtown lot can cost more in lost units than it adds in rent. Look for shared or municipal parking agreements and ask about parking requirement reductions.
Building systems and hidden costs
What hidden costs catch investors off guard in a building conversion?
The most common surprises are utility separation, egress and fire separation, structural repairs, and municipal requirements. Investors often underestimate new electrical service and metering, sprinklers and alarms, a second exit stair, elevator work, accessibility upgrades, hazardous material abatement, and utility tap or impact fees. Approvals, inspections, and permitting delays also add carrying costs. Budget a contingency and get contractor and code consultant input before closing.
Can an older building's existing electrical service support apartments?
Often not without upgrades. Residential units need individual panels, kitchen and laundry circuits, and enough service capacity for HVAC and appliances, which older commercial buildings may lack. An electrician or engineer should calculate the required load, and the local utility should confirm whether a new service, transformer, or meter bank is needed, since those costs and lead times can be significant.
Will a converted building need individual utility meters for each unit?
Usually electricity is metered by unit, while water and gas may be master-metered depending on local codes and utility rules. Individual metering lets tenants pay their own usage, which lowers operating costs and makes the property easier to finance and sell. If water or gas stays master-metered, consider submetering or a utility billing program where allowed, and build those costs into rents.
How do you know if an older building's HVAC system needs replacement during a conversion?
Have an HVAC contractor or mechanical engineer assess the age, condition, and capacity of the system. Commercial systems designed for office or retail use rarely suit apartments, which need individual controls and separate zones, so most conversions install new unit-by-unit systems. Plan for replacement unless the equipment is recent and can be adapted; reusing old systems usually raises operating costs and tenant complaints.
How do you find deferred maintenance hidden behind the walls of an older building?
Through targeted investigation before closing. Order a property condition assessment, structural and roof inspections, camera scoping of sewer lines, and an environmental survey for asbestos and lead paint. Ask to open small wall and ceiling sections in key areas. Even then, some issues appear only during demolition, so keep a meaningful contingency and negotiate the price around what you find.
How should ongoing maintenance costs be planned for in an older converted building?
Budget higher than for new construction and fund capital reserves from the start. Roofs, masonry, windows, plumbing, and elevators in older buildings need regular attention, even after renovation. A conversion that replaces most systems can lower near-term maintenance, but the shell still ages. Set an annual reserve per unit and schedule periodic inspections of the roof, facade, and drainage.
Will a converted building be easy to manage once it is occupied?
It can be, if the design anticipates operations. Individual utility meters, durable finishes, secure entry, adequate trash and storage areas, and modern building systems reduce management headaches. Small buildings with a few units can be self-managed, but mixed-use buildings with commercial tenants require more lease and maintenance oversight. Unique historic features may need specialized repairs, so budget for them.
Hotel and motel conversions
What should you analyze before converting a hotel or motel into apartments?
Start with acquisition price per room, the cost to add kitchens and enlarge units, zoning, and achievable rents. Many hotel rooms lack kitchens and are small, so conversion may mean combining rooms or creating efficiency units. Check plumbing and electrical capacity, parking, local demand for small units, and whether the city offers incentives for housing conversions. Underwrite lease-up and operating costs as apartments, not hotel revenue.
Are hotel-to-housing conversions still happening?
Yes, they continue in many markets, especially with older motels and limited-service hotels that struggle to compete as hospitality. Some cities and states have supported these projects as a faster way to add housing, but the economics depend heavily on purchase price, conversion costs, and zoning. Deals often work best as efficiency or workforce units rather than luxury apartments.
Do developers change unit layouts when converting motels into housing?
Often yes. Some keep single rooms and add kitchenettes for efficiency units, while others combine two rooms into a one-bedroom unit with a full kitchen. The choice depends on local demand, zoning minimum unit sizes, and plumbing locations. Combining rooms lowers the unit count but can produce higher rents and steadier tenants.
Can a commercial space under 2,000 square feet be converted into a micro-hotel or short-term rental?
Possibly, if zoning and building codes allow lodging or short-term rentals in that location. A small space might support a few guest rooms or suites, but each must meet fire, egress, and accessibility requirements, and some cities restrict short-term rentals. Compare likely occupancy and room rates against conversion and operating costs. In a joint venture, define each partner's capital, work responsibilities, and exit rights in writing.
Historic tax credits
How difficult is the historic tax credit approval process?
It is detailed but manageable with an experienced consultant or architect. The 20% federal historic tax credit requires the building to be a certified historic structure and the work to meet the Secretary of the Interior's Standards for Rehabilitation, reviewed through the State Historic Preservation Office and the National Park Service in a three-part application. Applying before construction is critical because unapproved work can disqualify the project.
Do historic rehabilitation tax credits make sense for a smaller renovation project?
Sometimes. The federal credit equals 20% of qualified rehabilitation expenses, claimed over five years, but the rehabilitation must be substantial, generally exceeding the greater of $5,000 or the building's adjusted basis. Consultant, design, and compliance costs can eat into the benefit on small projects. Some state credits have lower thresholds. Run the numbers with a tax advisor before committing.
How does the state historic tax credit process work through final certification and credit issuance?
State programs vary, but most follow the federal three-part model: certify the building, approve the proposed work, then certify the completed work before issuing credits. Before issuance, the state may require proof of ownership, cost certification, and the taxpayer or entity receiving the credit. Tennessee has historically not had a broad state historic tax credit, so confirm current availability with the Tennessee Historical Commission.
What happens if a property is sold between final certification and historic tax credit issuance?
It can jeopardize the credit. Federal historic credits can be recaptured if the property is sold within five years after it is placed in service, and state credits often go to the owner of record or a designated taxpayer at issuance. A transfer during the process may require state approval or transfer documentation. Coordinate with the state historic preservation office and a tax attorney before any ownership change.
Downtown revitalization grants
What should you ask at a downtown revitalization grant meeting before buying an older building?
Ask what costs qualify, the maximum award, matching requirements, the application deadline, design standards, and whether work started before approval is eligible. Also ask about the review timeline, required documentation, and how payments are made. Find out whether the grant comes with restrictions such as minimum ownership periods, occupancy requirements, or repayment if the property sells early.
Is grant money allocated to a downtown building actually committed?
Not until you have a signed grant agreement. A program announcement or verbal approval does not guarantee funds, which may depend on budget availability, final approval, and completion of specific work. Get the commitment in writing with the amount, eligible work, deadlines, and payment terms before relying on it in your budget or loan application.
What renovation expenses usually qualify for downtown revitalization grants?
Most programs fund exterior and code-related work such as facade restoration, storefronts, windows, signage, masonry, roofs, and sometimes fire protection or accessibility upgrades. Interior finishes, furniture, and routine maintenance are often excluded. Each program sets its own list, so get the guidelines in writing and have contractors itemize eligible costs separately.
Are downtown renovation grants paid up front or reimbursed after the work is done?
Usually reimbursed after the work is complete and inspected. Owners typically pay contractors first, then submit invoices, proof of payment, and photos for reimbursement. Some programs pay in stages, but few pay in advance. Plan your financing so you can carry the full cost until the grant is paid.
What happens if a grant-funded renovation goes over budget or does not meet grant requirements?
The owner usually absorbs overruns, because most grants are capped at the approved amount. If the work does not meet program design standards or deadlines, the grant may be reduced or denied, and some agreements require repayment if conditions are violated later. Get change orders approved by the program before work proceeds and keep detailed records.
Risk, deal structure, and scaling
Does an adaptive reuse deal still work if it takes longer, costs more, or leases up slower than planned?
Only if you stress-test it before buying. Run scenarios with a 10% to 20% cost overrun, a delay of several months, and slower lease-up, and confirm the project still covers debt service and returns capital. If any single setback wipes out the return, reduce the purchase price, add contingency, or line up more equity. Adaptive reuse deals commonly face at least one of these problems.
Can buy, entitle, convert, stabilize, and refinance become a repeatable adaptive reuse model?
Yes, but each building is different, so repeatability comes from process rather than identical projects. Developers who scale reuse standardize due diligence, contractor relationships, financing partners, and design choices. The refinance step depends on appraised value and interest rates, so the model fails when stabilized value does not exceed total cost. Start with a track record of smaller wins.
How should a 50/50 joint venture be structured with a hands-on partner who contributes construction capital?
Put it in a written operating agreement that defines capital contributions, who manages construction, how overruns are funded, how returns are distributed, and how decisions and deadlocks are handled. Many JVs return contributed capital first, then split profits. Include buy-sell provisions, exit timing, and what happens if a partner cannot fund. An attorney should draft the agreement.
What do investors want to see before funding a second adaptive reuse project?
Investors want proof the first project worked: actual costs versus budget, lease-up timing, rents achieved, and returns delivered. They also look for a clear pipeline, a repeatable team, realistic underwriting, and evidence that the sponsor manages risk and communicates well. A transparent explanation of what went wrong on the first deal and how it was fixed builds confidence.
Sources
- National Park Service — Historic Preservation Tax Incentives — the 20% federal historic rehabilitation tax credit
- National Park Service — The Secretary of the Interior's Standards for Rehabilitation — the standards rehabilitation work must meet
- Tennessee Historical Commission — Federal Historic Tax Credit Program — Tennessee's State Historic Preservation Office review
- IRS — Opportunity Zones — Qualified Opportunity Fund rules and current guidance
Primary sources for the page's material claims. Figures attributed to third parties are as reported by those sources on the dates shown; Carson's views are labeled as his opinion.
Selling or buying commercial property? Let's talk.
Brokerage and equity participation for commercial real estate owners, investors, and family offices — worldwide, through the eXp Commercial platform.

Carson Jones
Carson Jones is the host of Carson's Corner: Commercial Real Estate, author of The Red Flag Playbook, a licensed commercial real estate advisor and business broker, and the founder of Passive Investments. With 18 years of experience as an entrepreneur and 12 years specializing in passive investing, Carson works with high-net-worth individuals, family offices, business owners, and sophisticated investors as a broker and principal.
Carson holds a BBA in Finance from Baylor University and his Tennessee commercial real estate license (#382989). He actively pursues acquisition and equity opportunities across the United States and abroad through a worldwide network of qualified buyers, family offices, institutional investors, and top-tier developers.