Why will many rescue recapitalizations in commercial real estate fail?
Many rescue recapitalizations will fail because they plug refinance gaps without fixing the core problem: the property's value and income no longer support the original basis. More than $4 trillion in commercial mortgages mature between 2025 and 2029, according to S&P Global, and Carson's view is that Class B and C cap rates of 8%–9%+ by 2028 are very possible even if interest rates fall.
Key takeaways
- Commercial mortgage maturities peak around $1.26 trillion in 2027, according to S&P Global.
- Many maturing loans were written at 3%–4% rates and must refinance closer to 6%–7% or higher, turning previously stable properties into deals that no longer cover their debt.
- The textbook link between lower rates, compressed cap rates and higher values broke down during the 2009 cycle and could break down again.
- Unlike 2008, much of today's CRE risk sits in smaller regional banks and private capital structures without the systemic backstops of the largest institutions.
- Carson favors smaller submarkets of 50,000 to 200,000 people that are not heavily oversupplied and are unlikely to become so because of their size.
The Rescue Recaps…..That Won’t Work
$4 trillion in commercial real estate debt is maturing into a world that no longer exists. Here’s why the usual rescue capital playbook is about to fail spectacularly.
Imagine pouring fresh rescue capital into a deal… only to watch valuations keep falling and debt service coverage collapse anyway. That scenario isn’t hypothetical — it’s the 2026-2028 playbook, even with lower rates.
Rates & Recession
Whether the war drags on or comes to an end, interest rates are likely headed lower.
If the conflict persists, a recession would almost certainly force the Fed to cut rates. If the war ends, lower energy prices would ease inflation, again opening the door to rate cuts.
Or, the new Fed Chair could simply deliver aggressive easing right out of the gate.
The direction of travel for rates “appears” downward.
But the textbook relationship ("lower rates compress cap rates and lift values") broke down completely during the 2009 cycle and could very well break down again over the next several years and here is why.
Supply
On top of an already over supplied sunbelt, there are roughly 54 million renters in the U.S. and roughly 4 million immigrants being deported, that number is heading towards 10% of renters being deported.
One of the least discussed pressure valves in housing is multigenerational living. During the 2008 crisis, millions of Americans doubled up under one roof. How does AI job replacement fit into this?
Why is the commercial real estate maturity wall a problem?
More than $4 trillion in commercial mortgages mature between 2025 and 2029, peaking around $1.26 trillion in 2027, according to S&P Global. Many were written at 3–4% rates and must now refinance closer to 6–7% or higher, a gap large enough to turn once-stable properties into deals that no longer cover their debt.
This isn’t a vibe — it’s a maturity schedule. More than $4 trillion in commercial mortgages mature between 2025 and 2029, peaking around $1.26 trillion in 2027, according to S&P Global. Many were written at 3–4% rates and now must refinance closer to 6–7%+, creating a gap large enough to turn previously stable properties into deals that no longer cover their debt.
Why will many rescue recapitalizations fail?
Rescue capital comes in at high preferred returns with senior rights to plug refinance gaps and buy time, but it rarely fixes the core problem: the property's value and income no longer support the original basis. Recaps also did not plan for values falling further, with 8–9%+ cap rates on Class B and C assets possible by 2028.
Rescue recapitalizations are when new “rescue” capital comes into a struggling deal — usually at high preferred returns and with senior rights in the capital stack — to plug refinance gaps and buy time. The problem is they often don’t fix the real issue: the property’s value and income no longer support the original basis.
What the recapitalizations didn’t plan on was valuations going even lower by 2028, like 8-9%+ cap rates on Class B & C……very possible even with lower rates.
Some recapitalizations will ultimately be successful, not all markets and assets are created equally.
How could CRE distress spread into a broader liquidity crisis?
Commercial real estate touches regional banks, pension funds, insurers, debt funds, CMBS and private investors, so when its liquidity dries up, credit tightens across the economy. Lending slows, development stalls and investors turn defensive, and unlike 2008, much of the risk sits in smaller banks and private structures without the same systemic backstops.
The danger is the ripple effect. Commercial real estate impacts regional banks, pension funds, insurers, debt funds, CMBS, and private investors. When liquidity dries up in CRE, credit tightens across the economy — lending slows, development stalls, and investors turn defensive. Unlike 2008, much of today’s risk sits in smaller regional banks and private capital structures without the same systemic backstops as the largest institutions.
Where is the opportunity in today's CRE distress?
Distress creates winners as well as losers. Carson favors smaller submarkets, towns or suburbs of 50,000 to 200,000 people, because they are not heavily oversupplied and, given their size, are unlikely to become oversupplied, which makes their rents and values more resilient than overbuilt Sun Belt metros as loans reset.
None of this is doom for everyone. Distress always creates winners alongside losers.
Right now, I love the smaller submarkets. Towns or suburbs with populations between 50,000 to 200,000, that aren’t way over supplied and probably likely won’t be due to their size.
Frequently Asked Questions about Rescue Recaps and CRE Liquidity Risk
What is a rescue recapitalization in commercial real estate?
A rescue recapitalization is new capital that enters a struggling deal to plug a refinance gap and buy time. It usually comes in at high preferred returns and with senior rights in the capital stack. The weakness is that it often does not fix the underlying issue, which is that the property's value and income no longer support the original basis.
How big is the commercial real estate maturity wall?
More than $4 trillion in commercial mortgages mature between 2025 and 2029, peaking around $1.26 trillion in 2027, according to S&P Global. Many of those loans were written at 3% to 4% interest rates and now must refinance closer to 6% to 7% or higher, a gap large enough to push previously stable properties below debt coverage.
Will lower interest rates save struggling CRE deals?
Not necessarily. Carson expects rates to trend lower, but the textbook relationship in which lower rates compress cap rates and lift values broke down during the 2009 cycle and could break down again. His view is that Class B and C properties could see cap rates of 8% to 9% or higher by 2028, which many recapitalizations did not plan for.
Why does CRE liquidity risk matter beyond real estate?
Commercial real estate is tied to regional banks, pension funds, insurers, debt funds, CMBS and private investors. When liquidity dries up in CRE, credit tightens across the economy: lending slows, development stalls and investors turn defensive. Unlike 2008, much of the current risk sits in smaller regional banks and private capital structures that lack the backstops of the largest institutions.
Where does Carson see opportunity in the CRE downturn?
Carson's position is that distress creates winners alongside losers, and he currently favors smaller submarkets: towns or suburbs with populations between 50,000 and 200,000. These markets are not heavily oversupplied and are unlikely to become so because of their size, in contrast to the already oversupplied Sunbelt.
CRE Liquidity and Lending Risk Questions Investors Ask
These are the questions investors and borrowers most often ask about bank failures, debt fund leverage, bridge lending, and today's debt market. Answers explain how the risk moves through the system.
Bank failures and what they mean for borrowers
How are commercial real estate owners affected when banks fail or pull back?
Mainly through less available credit and tougher loan terms. Regional and community banks are major commercial real estate lenders, so when some fail or get nervous, survivors cut new lending, lower loan-to-value limits, and demand larger deposits or recourse. Borrowers with near-term maturities feel it most. Existing loans at a failed bank usually remain in force under a new owner, but refinancing gets harder across the whole market.
What happens to a construction loan if the lending bank fails midway through funding?
The loan doesn't disappear, but future draws can be delayed. The FDIC takes over as receiver and either transfers the loan to an acquiring bank or holds it while it is sold. Unfunded commitments are not always honored right away, so a project can stall while the borrower waits or seeks replacement financing. Borrowers should keep close contact with the receiver, document draw requests carefully, and get legal advice about their rights under the loan.
What happens to a failed bank's commercial real estate loan book?
The FDIC, as receiver, sells it. Some loans go to the bank that acquires the deposits; the rest are marketed to investors, often in pools or through joint ventures in which the FDIC keeps a share of the profits. Borrowers' loan terms stay the same, but the new holder may be less flexible on extensions and modifications than the original relationship banker.
What happens to a commercial real estate loan when the lender gets bought?
The loan terms stay the same, but the relationship may change. The acquiring bank takes over the loan documents, rate, and maturity as written. What can change is appetite: the new owner may have different concentration limits, credit standards, or interest in the property type, so extensions, future advances, and renewals may be harder to get. Borrowers with near-term maturities should start conversations with the new lender early and line up alternatives.
What did the Credit Suisse collapse show about bank liquidity risk?
That confidence can drain a large bank faster than regulators can fix it. After years of losses and scandals, depositors pulled money rapidly in 2023, and Swiss authorities arranged an emergency takeover by UBS, wiping out certain bondholders. The lesson for real estate is that liquidity, not just solvency, decides whether a lender survives, and a lender's trouble can quickly limit credit to its borrowers.
How badly will downtown commercial real estate distress affect local economies?
It can hit city budgets and small businesses hard. Falling office values reduce property tax assessments, which cities rely on for revenue, and lower foot traffic hurts restaurants and retailers that depend on office workers. Local banks with heavy downtown loan exposure may also lend less. Cities that support conversions, mixed-use redevelopment, and residential growth downtown tend to recover faster.
How real estate debt funds are financed
How do real estate debt funds lever their loans, and how much leverage do they use?
Mostly by borrowing against their loans through repo lines, warehouse facilities, and CLOs. A fund originates a loan, then pledges it to a bank that advances a large share of the balance, letting the fund earn a spread on the borrowed money. Typical fund-level leverage varies widely by strategy, with senior bridge lenders often running a few times equity and conservative or mezzanine-focused funds using little or none.
How do repo lines work for real estate lenders?
A repo line lets a lender sell loans to a bank with an agreement to buy them back, which works as short-term secured borrowing. The bank advances a percentage of each loan's value and can demand more collateral if it marks the loan down. That margin-call feature is the danger: if values fall, the lender must post cash or sell assets quickly, which can force sales at the worst time.
What is the difference between repo lines, warehouse lines, and subscription facilities for debt funds?
They differ by what secures them. Repo and warehouse lines are secured by the loans the fund makes and are used to finance or hold those loans until they're sold or securitized; repo lines usually carry margin-call rights. Subscription facilities are secured by investors' unfunded capital commitments and bridge timing until the fund calls capital. Subscription lines are generally lower risk, while repo lines can amplify stress when loan values fall.
Bridge lending, CRE CLOs, and mortgage REITs
What are the risks in multifamily bridge lending?
Floating-rate loans on unstabilized properties carry the most risk when rates rise. Bridge loans made in 2021–2022 assumed quick renovations, rising rents, and cheap refinancing. Higher rates, expensive rate caps, and slower rent growth left many borrowers unable to refinance or cover interest. Lenders respond with modifications and extensions, but rising delinquencies, loan buybacks from securitizations, and foreclosures signal that losses are being recognized slowly.
What does CRE CLO data reveal about bridge loan stress?
It shows stress through delinquencies, modifications, and loan buyouts. Commercial real estate CLOs publish regular reports on each loan, so investors can track late payments, extensions, and assets that lenders repurchase or swap out of the pool. A rising number of modified or repurchased loans can mean the headline delinquency rate understates the problem. Read the trend over several reporting periods rather than a single month.
How do commercial mortgage REITs differ in risk?
By loan type, property mix, leverage, and funding sources. Some mortgage REITs focus on senior first-mortgage loans, others hold more office, bridge multifamily, or subordinate debt. Compare the share of loans on watch lists or non-accrual, office exposure, debt-to-equity, reliance on short-term repo versus term CLO funding, book value trends, and whether the dividend is covered by distributable earnings. Trading well below book value usually signals expected credit losses.
The CRE debt market today
What is the current commercial real estate debt market situation?
Credit is available but selective. Agency lenders, life companies, CMBS, and debt funds are lending on stabilized multifamily, industrial, and well-leased retail, while office and transitional assets still face tight terms. Banks remain cautious because of existing exposure. Spreads have narrowed from their peak, but loan sizes are limited by debt-yield and coverage tests, so many owners still need fresh equity to refinance maturing loans.
Where are commercial real estate loan spreads and debt pricing today?
Spreads have tightened from their 2023 highs, but all-in rates remain well above pre-2022 levels. Fixed-rate loans from agencies, life companies, and CMBS are generally priced as a spread over Treasury yields, while bridge and construction loans are priced as a spread over SOFR. The spread depends on property type, leverage, and sponsor. Get current term sheets from several lenders, because published averages lag the market.
What going-in and stabilized debt yields are lenders requiring today?
Debt yield equals net operating income divided by the loan amount, and lenders use it to cap loan size. For stabilized properties, many lenders look for debt yields in the high single digits to around 10%, with office and riskier assets higher. Bridge lenders accept lower going-in debt yields but underwrite to a stabilized debt yield the business plan must reach. Exact thresholds vary by lender and property type.
What does a sudden jump in SOFR mean for floating-rate commercial real estate borrowers?
A brief spike usually reflects funding-market strain, not a lasting rate change. SOFR can jump around month-end or quarter-end when cash is tight in the repo market. Short spikes have limited effect on borrowers whose loans reset monthly off Term SOFR. But repeated spikes can signal tighter liquidity in the financial system, which matters for lenders funded by repo lines. Borrowers should keep rate caps in place.
How is the debt market for life science office properties?
Tight. Lenders are cautious because vacancy has risen in many life science clusters, buildings are expensive to re-lease to new tenants, and conversions to other uses are costly. Well-leased properties with strong tenants can still get financing, mostly from life companies or relationship banks at conservative leverage. Speculative or partly vacant buildings often need rescue capital, extensions, or a sale to resolve maturing loans.
Equity scarcity and smaller assets
Why is there a shortage of LP and JV equity for ground-up multifamily development?
Because returns don't compensate for the risk right now. High construction costs, expensive debt, and uncertain exit cap rates have squeezed projected development returns close to what investors can earn buying existing buildings at a discount. Many institutional investors are also over-allocated or waiting for distributions from older funds. Equity is still available for projects with strong sponsors, low land basis, or incentives, but on tougher terms.
Is there a pricing discount for smaller real estate assets?
Yes, smaller assets often trade at higher cap rates and lower prices per unit. Fewer institutional buyers compete for them, financing comes mainly from local banks, and management is less efficient at small scale. That discount can be an opportunity, especially in smaller submarkets where well-capitalized investors can buy solid income at better yields. The trade-off is lower liquidity when it's time to sell.
Macro scenarios and history
How would stagflation affect commercial real estate?
It would be a difficult mix: higher rates and costs with weaker demand. Inflation raises operating, insurance, and construction costs and keeps interest rates elevated, while slow growth limits rent increases and tenant expansion. Properties with short leases and pricing power, such as apartments, self-storage, and hotels, can adjust rents faster. Long fixed leases without escalations lose value in real terms.
Is a recession coming for real estate?
No one can time it, but much of commercial real estate has already been through its own downturn. Values fell after 2022 even without a broad recession, because of higher interest rates. A recession would add weaker tenant demand and rising vacancies on top of that, hitting office, hotels, and weaker retail hardest. Owners with fixed-rate debt, long leases, and cash reserves are best positioned regardless of the timing.
What did real estate capital markets look like in 2008?
Credit markets nearly shut down. CMBS issuance collapsed, banks stopped lending, and property values fell sharply as forced sales met few buyers. Lenders at first extended loans, then foreclosed and sold distressed assets, and buyers with cash earned strong returns over the following decade. Unlike today, the 2008 crisis started in the banking system, while today's stress starts with higher interest rates and overleveraged properties.
Exposure and next steps
Who is most exposed to commercial real estate liquidity risk?
Smaller lenders and private capital, more than the largest banks. Commercial real estate touches regional banks, pension funds, insurers, debt funds, CMBS and private investors. Unlike 2008, much of today's risk sits in smaller regional banks and private structures without the systemic backstops of the largest institutions, and borrowers whose loans were written at 3%–4% and must refinance near 6%–7% feel the squeeze first.
What should owners do now if their loan matures soon or their lender is pulling back?
Start early and line up more than one path. Begin 12 to 18 months before maturity: order a current valuation, size a new loan at today's rates and debt-yield tests, and measure the gap against the payoff. Then compare refinancing with fresh equity, an extension with paydowns, preferred equity, or a sale. See The Rescue Recaps That Won't Work for how rescue capital affects existing equity.
Sources
- S&P Global Market Intelligence — "CRE maturity wall reaches $950B in 2024, peaks in 2027" (Aug 2024) — commercial mortgage maturity wall and its 2027 peak
- Mortgage Bankers Association — "17 Percent of Commercial and Multifamily Mortgage Balances to Mature in 2026" (Feb 9, 2026) — about $875 billion maturing in 2026, after $957 billion scheduled for 2025
Primary sources for the page's material claims. Figures attributed to third parties are as reported by those sources on the dates shown; Carson's views are labeled as his opinion.
Selling or buying commercial property? Let's talk.
Brokerage and equity participation for commercial real estate owners, investors, and family offices — worldwide, through the eXp Commercial platform.
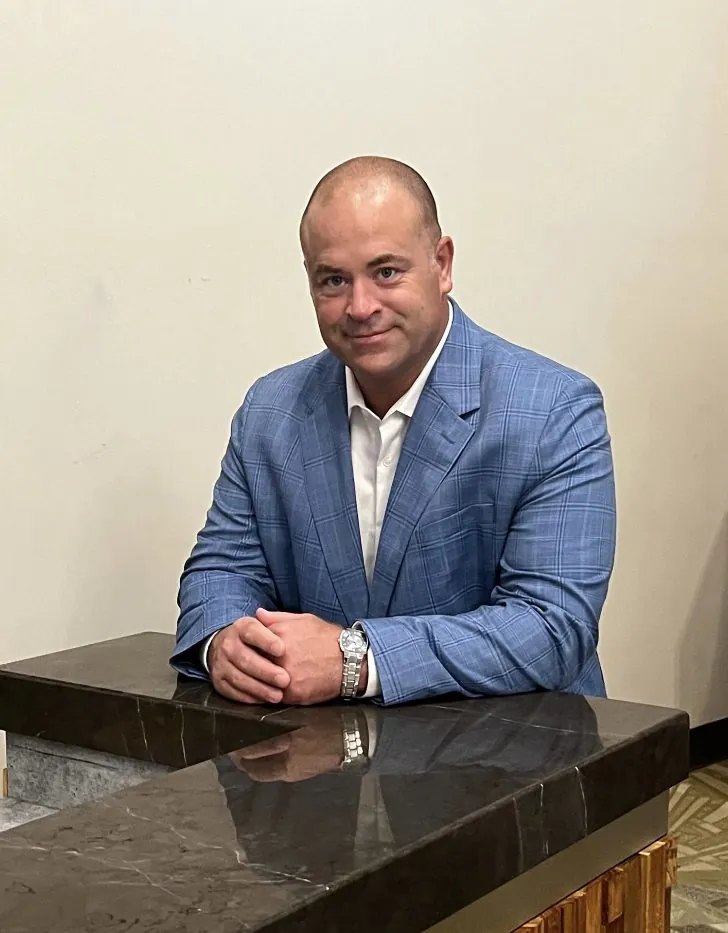
Carson Jones
Carson Jones is the host of Carson's Corner: Commercial Real Estate, author of The Red Flag Playbook, a licensed commercial real estate advisor and business broker, and the founder of Passive Investments. With 18 years of experience as an entrepreneur and 12 years specializing in passive investing, Carson works with high-net-worth individuals, family offices, business owners, and sophisticated investors as a broker and principal.
Carson holds a BBA in Finance from Baylor University and his Tennessee commercial real estate license (#382989). He actively pursues acquisition and equity opportunities across the United States and abroad through a worldwide network of qualified buyers, family offices, institutional investors, and top-tier developers.