Why is commercial real estate transaction volume frozen?
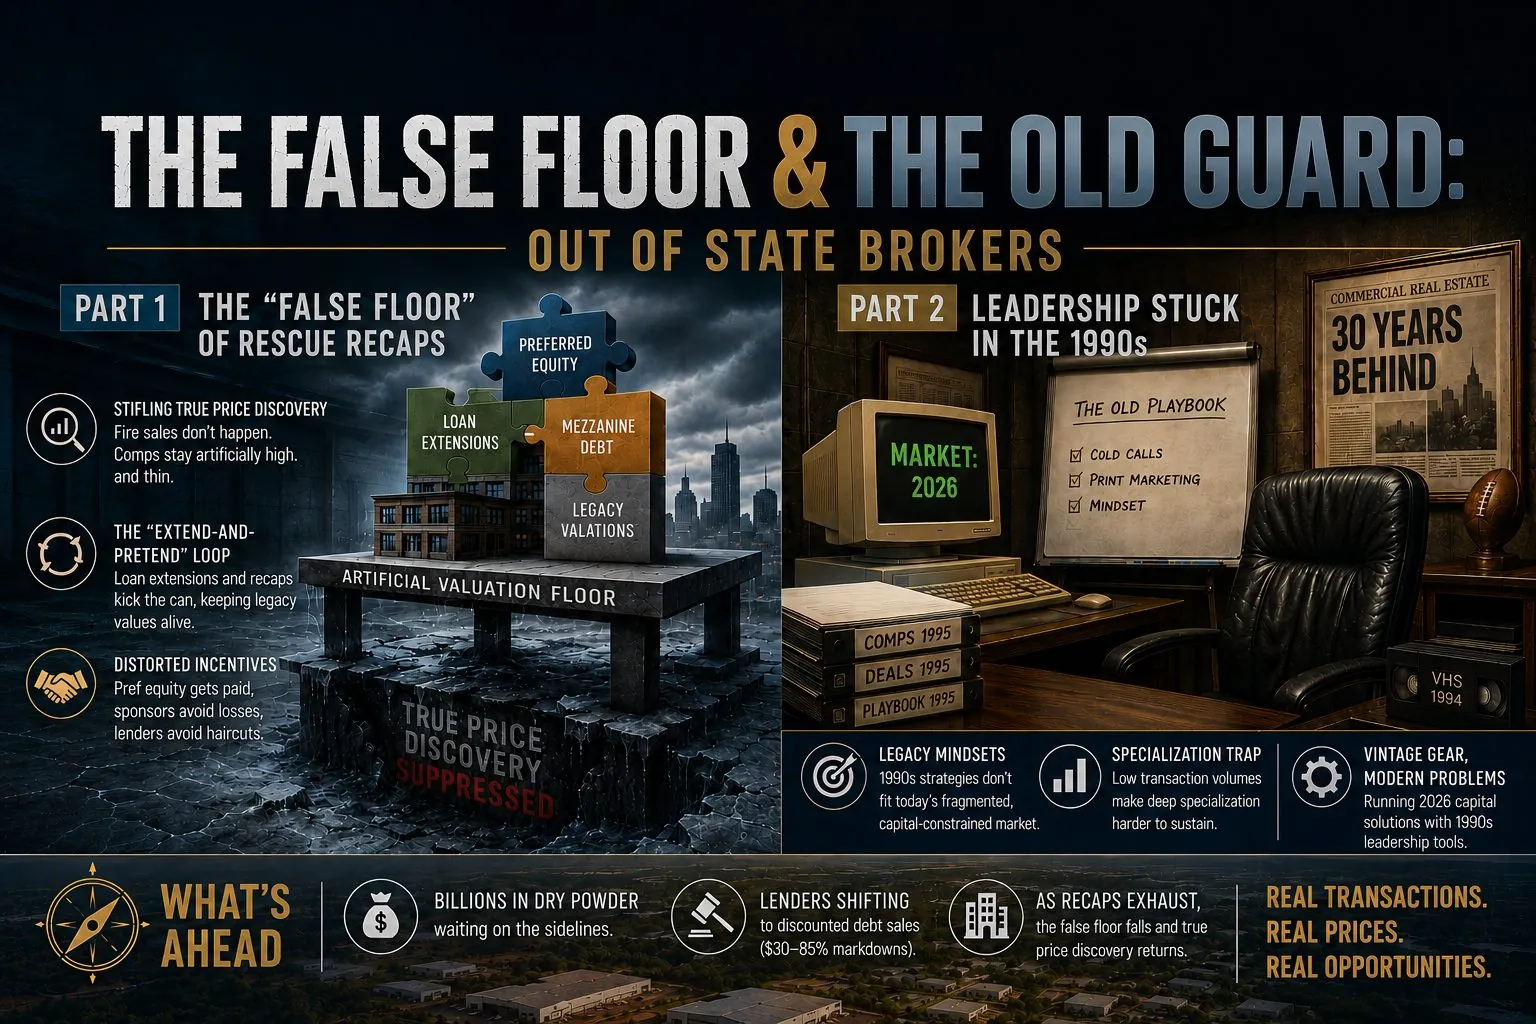
Carson's view is that CRE transaction volume is frozen because rescue recapitalizations, such as preferred equity and mezzanine debt, created a false valuation floor. By keeping distressed assets off the market and pairing capital with loan extensions, they hold comps artificially high and thin, so bid-ask spreads stay wide and true price discovery is delayed until lenders take losses.
Key takeaways
- Preferred equity investors in rescue recaps lock in returns of 12% to 18% or more, which gives everyone inside the deal a reason to wait rather than sell.
- Lenders are shifting from loan modifications to discounted debt sales at 30% to 85% markdowns, which the page expects to restore real price discovery.
- Fewer than 50 multifamily transactions had closed in Tennessee in the year of writing, which the page uses to question broker specialization at that volume.
- Carson argues owners increasingly hire the broker who can create the most competition for an asset, including brokers from outside their local market or state.
- Northeast Tennessee, just north of Asheville, has 1.2 million people within 60 miles and draws demand from 12 million-plus annual visitors to Great Smoky Mountains National Park.
If the CRE engine feels like it's idling, you're not imagining it.
Transaction volumes are suppressed, bid-ask spreads are stubbornly wide, and true price discovery is a moving target.
How do rescue recaps create a false pricing floor?
Preferred equity and mezzanine debt kept distressed assets from being sold after rates rose, so fresh, realistic comps never formed. Lenders paired these infusions with loan extensions to avoid writing off losses, leaving properties valued at legacy levels that ignore today's cap rates and NOI, and keeping bid-ask spreads wide across the market.
Rescue capital — preferred equity, mezzanine debt — was pitched as the hero of the post-2022 rate era. When maturities hit and valuations dropped, pref equity plugged the gap and saved sponsors from forced sales.
It's not fraudulent. Many deals just need time. But it created a false valuation floor.
Here's how it delays the reset:
→ It stifles price discovery. Distressed sales set fresh, realistic comps. Rescue recaps keep those assets off the market, so official comps stay artificially high and thin.
→ It fuels "extend-and-pretend." Lenders pair capital infusions with loan extensions to avoid writing off losses. Properties keep operating on legacy values that don't reflect today's cap rates or NOI.
→ It distorts incentives. Pref investors lock in 12–18%+ returns. Sponsors avoid a reputation-damaging loss. Lenders avoid a haircut. Everyone inside the deal wins by waiting — while the market stays stuck.
True floors form through transactions, not restructurings. And the bad news is not everybody wins — many rescue recaps will fail, just delaying the inevitable. The notes will come due.
The playbook: wait out the recaps. When lenders finally cut losses through discounted debt sales or foreclosures, cleaner entry points with a realistic basis open up.
Why do traditional CRE brokerage practices fall short in a frozen market?
The industry's playbook is about 30 years old and was built for high transaction volume. With fewer than 50 multifamily sales closing in Tennessee this year, narrow specialization struggles, and Carson argues the winners will be brokers running sophisticated marketing and capital-stack strategies rather than leaning on cap rates and comps alone.
The freeze exposes a deeper problem: our industry's playbook is 30 years old.
Fewer than 50 multifamily transactions have closed in Tennessee this year. Now ask how many brokers "specialize" in multifamily. Can specialization even survive at that volume?
CRE brokerage is still running Joe Montana-era leadership in a 2026 market — fragmented, data-rich, and capital-constrained. You can't solve today's capital stack problems with 1990s plays.
Brokers are left running modern playbooks with vintage gear.
Tomorrow's winners will be those who execute sophisticated marketing strategies—not those who rely on outdated industry jargon like cap rates and comps from a decades-old CRE playbook.
The savviest property owners aren't hiring based on who can quote the most comps. They're hiring the broker who can create the most competition for their asset. That's why many don't hesitate to bring in brokers from outside their local market or state when they believe those brokers can deliver superior exposure and execution.
Does your current brokerage allow you to transact in other states?
What will end the CRE transaction freeze?
Lenders are shifting from loan modifications to discounted debt sales at 30–85% markdowns, and billions of dollars in dry powder are waiting on the sidelines. As assets come out of exhausted recap structures, the artificial floor gives way to real price discovery, and transaction volume and genuine buying opportunities return with it.
The limbo can't last. Billions in dry powder sit on the sidelines, and lenders are shifting from loan modifications to discounted debt sales — 30–85% markdowns.
As assets emerge from exhausted recap structures, the artificial floor gives way to real price discovery.
Transaction volume — and real opportunity — comes back with it.
One thing that will never change is trust and relationships matter.
I'm currently marketing several opportunities in Northeast Tennessee — just north of Asheville — that actually pencil. The pipeline includes coworking, boutique hotel, and loft conversion projects. The fundamentals are hard to ignore: 1.2 million people within 60 miles and 12+ million annual visitors to Great Smoky Mountains National Park, driving durable demand for hospitality, residential, and experiential mixed-use.
Link: https://go.passive.investments/244BroadSt
Link: https://go.passive.investments/247BroadSt-OM
Frequently Asked Questions about the CRE Pricing Floor
What is a false pricing floor in commercial real estate?
A false pricing floor is an artificially high valuation level that persists because distressed assets are recapitalized instead of sold. Rescue capital such as preferred equity and mezzanine debt keeps those properties off the market, so fresh, realistic comps never form. Official comps stay high and thin, and properties keep operating on legacy values that do not reflect current cap rates or NOI.
How do rescue recaps delay the CRE price reset?
Rescue recaps delay the reset in three ways. They stifle price discovery by keeping distressed assets off the market. They fuel extend-and-pretend, as lenders pair capital infusions with loan extensions to avoid writing off losses. And they distort incentives: preferred investors earn 12% to 18% or more, sponsors avoid a visible loss, and lenders avoid a haircut, so waiting benefits everyone inside the deal.
Are rescue recapitalizations fraudulent?
No. Carson's view is that rescue recaps are not fraudulent and that many deals simply need time. The problem is the side effect: they create a false valuation floor that keeps the broader market stuck. He also expects many rescue recaps to fail, only delaying the inevitable, because the underlying notes will still come due and true floors form through transactions, not restructurings.
What will restart CRE transaction volume?
Transaction volume is expected to return as lenders move from loan modifications to discounted debt sales, with markdowns of 30% to 85%, and as assets emerge from exhausted recap structures. That gives way to real price discovery. Billions of dollars in dry powder are waiting on the sidelines, and the suggested approach is to wait out the recaps for cleaner entry points with a realistic basis.
Why does Carson think CRE brokerage needs to change?
Carson argues the industry's playbook is about 30 years old while the market is fragmented, data-rich and capital-constrained. With fewer than 50 multifamily transactions closed in Tennessee in the year of writing, he questions whether narrow specialization can survive. In his view, owners now favor brokers who create the most competition for an asset through sophisticated marketing, even brokers from other markets or states.
CRE Pricing and Transaction Volume Questions Investors Ask
These are the questions owners, buyers, and acquisitions professionals most often ask about stalled deal flow, cap rates, and pricing. Answers focus on how pricing actually gets set when the market is thin.
Why deals aren't getting done
Why doesn't anyone want to sell commercial real estate right now?
Because owners with stable income and fixed-rate debt have no reason to sell at a discount. Many locked in low-rate loans before 2022, so holding is cheap and selling means giving up that financing and accepting a lower price. Owners who don't face a maturity or capital need simply wait. Supply only comes to market when loans mature, funds hit the end of their lives, or lenders force the issue.
Why do commercial real estate deals stall even when the numbers on paper make sense?
Usually because financing, diligence, or the seller's expectations shift after the deal is agreed. Common causes include a lender cutting loan proceeds, an appraisal coming in low, rising insurance or tax estimates, environmental or physical issues found in diligence, or a seller who won't adjust price to reflect them. Deals that pencil only with optimistic assumptions break at the first surprise; buyers with conservative underwriting and committed capital close more often.
Is anyone actually getting commercial real estate deals done right now?
Yes, but far fewer than in 2021–2022, and mostly specific kinds of deals. Activity tends to cluster around motivated sellers facing maturities, lender-driven sales and note sales, smaller assets financed by local banks, owner-users, and well-capitalized buyers paying cash or assuming existing low-rate loans. Many acquisitions teams report long stretches of underwriting with few closings, because the spread between buyer and seller pricing remains too wide on most marketed assets.
What does commercial real estate transaction volume look like in 2026?
Industry trackers show activity well below the 2021–2022 peak, though off the lows of 2023–2024. Deal flow has improved unevenly: industrial, multifamily, and necessity retail trade more readily, while office volume remains thin outside distressed sales. Much of the recovery is driven by forced sellers and refinancing deadlines rather than broad confidence. A full rebound still depends on sellers accepting lower prices and long-term rates stabilizing.
Why would a buyer walk away from a large nonrefundable deposit on a commercial property?
Because closing would cost them more than the deposit. If financing costs rise, the asset's value falls, or diligence turns up problems after the deposit goes hard, a buyer may calculate that losing the deposit is cheaper than overpaying or closing into a loss. On large deals, a deposit of a few percent of the price can be small compared with a value drop of 10% or more.
Interest rates, spreads, and repricing
When will commercial real estate reprice if the 10-year Treasury stays elevated?
It reprices as loans mature and owners are forced to transact. Prices adjust deal by deal, not all at once. With long-term rates high, cap rates can't fall much, so values for overleveraged assets have to come down to meet buyers. Rescue capital and loan extensions delay that process, which is why the reset has taken years rather than months and is still working through office, bridge-financed multifamily, and other troubled segments.
Why are cap rate spreads over Treasuries so thin?
Because property prices haven't fully adjusted to higher Treasury yields. Cap rates rose more slowly than bond yields after 2022, so the extra return for owning real estate instead of risk-free Treasuries shrank. Sellers holding out for older prices and rescue capital propping up values keep cap rates artificially low. Historically, thin spreads have been followed either by falling rates or by rising cap rates and lower prices.
Why buy multifamily when Treasury yields are nearly equal to multifamily returns?
Only if you expect growing income or can buy below today's typical pricing. A Treasury pays a fixed return with no risk, while an apartment's going-in yield should be higher to compensate for operations, leverage, and illiquidity. When the two are close, the case rests on rent growth, value-add upside, tax benefits such as depreciation, or a discounted purchase. Without one of those, the Treasury is often the better risk-adjusted choice.
How do cap rates relate to interest rates and cash-on-cash returns?
Cap rates tend to move with interest rates, and the gap between them drives cash-on-cash returns. The cap rate is net operating income divided by price. If the loan's interest rate is below the cap rate, leverage boosts cash-on-cash returns; if the rate is above it, borrowing reduces them, called negative leverage. Rising rates push buyers to demand higher cap rates, which lowers prices for the same income.
Where are we in the commercial real estate market cycle?
Most sectors are in a late correction or early recovery phase, with wide differences by property type. Prices fell after rates rose in 2022, and many owners are still working through refinancing. Industrial and necessity retail are further along, multifamily is absorbing a supply wave, and office remains in a deeper reset. Watch distressed sales, lender behavior, and new construction starts for signs of the next phase.
Cap rates, discount rates, and pricing an offer
What cap rates are office transactions trading at?
Office cap rates vary so widely today that a single number is misleading. Well-leased, newer buildings with strong tenants still trade at relatively low cap rates, while commodity older buildings sell at much higher cap rates or are priced per square foot because income is uncertain. Many office sales are distressed or land-value plays where cap rates barely apply. Recent local comparable sales and lease rollover matter more than national averages.
How do you determine exit cap rates?
A common rule is to set the exit cap rate above the going-in rate. Many underwriters add roughly 10 to 25 basis points per year of hold, or a flat premium, to reflect an older building and uncertainty about future rates. Then cross-check against long-term averages for the property type and market, and test the deal at several exit caps. If the deal only works with an exit cap at or below today's, the plan depends on market luck.
What discount rate should you use in today's commercial real estate market?
Start with the return you could earn elsewhere and add risk premiums. A practical approach is the current Treasury yield plus a premium for the property type, location, lease risk, and leverage, checked against what investors are actually targeting for similar assets. Higher interest rates mean discount rates are higher than in 2021, which lowers present values for the same cash flows. Use a range, not a single number, and see how sensitive value is.
How do experienced investors arrive at an offer price?
They work backward from the return they need. Investors underwrite realistic income and expenses, apply current financing terms, set a conservative exit cap rate, and solve for the price that hits their target return. They then check that figure against comparable sales, replacement cost, and the seller's likely debt payoff. The final offer reflects all three: what the numbers support, what the market has paid, and what the seller can accept.
How do you stay current on commercial real estate pricing when you're not actively buying?
Keep underwriting deals and talking to people who close them. Review offering memorandums, track closed sales in your target markets, and ask brokers and lenders where recent deals actually traded versus their asking prices. Follow lender term sheets for current debt pricing, and read quarterly reports from research firms. Underwriting a few deals a month, even without bidding, keeps your assumptions grounded in the market.
Owner decisions: hold, sell, or fix
How should owners evaluate hold-or-sell decisions today?
Compare the return on today's equity to what that equity could earn elsewhere. Estimate the property's current value, subtract the loan and selling costs, and ask whether holding that net equity will earn more than redeploying it. Factor in the loan maturity, upcoming capital needs, tax consequences such as depreciation recapture and 1031 options, and how much below-market financing you'd give up by selling.
Would you sell a property at a discount to avoid renovation costs?
Sometimes, yes, if the discount is smaller than the full cost and risk of renovating. Count the hard and soft costs, lost rent during the work, carrying costs, financing, and the chance of overruns. If a buyer with lower costs or a different plan will pay a price that leaves you better off than finishing the work yourself, selling as-is can be the higher-return choice. Many owners underestimate the time and capital a renovation consumes.
What should I do about an unsolicited offer on my commercial property?
Treat it as information, not an obligation. Get a current valuation or broker opinion of value, verify the buyer's ability to close, and compare the offer with your hold plan and tax position. An unsolicited offer often signals more demand than you realized, so testing the market quietly with a few qualified buyers may produce a better price. Don't sign a letter of intent with exclusivity until you know what the property is worth.
Why would an owner sell a commercial property off-market?
For privacy, speed, and control. Off-market sales avoid alerting tenants, employees, or competitors, and let the seller negotiate with a few known buyers. They can also suit sellers who want certainty of close over the last dollar. The trade-off is price: limited exposure can leave money on the table, so off-market sellers should still benchmark offers against comparable sales and a professional valuation.
Why is a commercial property priced far below comparable sales?
Usually because something the comparables don't have is wrong with it. Common reasons include short remaining leases or a vacating tenant, deferred maintenance, environmental contamination, title or zoning problems, below-market leases, a forced or lender-driven sale, or a difficult location. A low price can be a real opportunity, but buyers should identify the reason through diligence before treating it as a bargain.
Why do owners keep zombie malls alive even when towns want them redeveloped?
Because selling or redeveloping would force them to recognize a loss. Owners and lenders may keep a struggling mall running to avoid writing down the value, to preserve tax benefits, or while waiting for a better offer. Anchor leases and reciprocal easement agreements can also give multiple parties veto rights over redevelopment. Change usually comes when the debt defaults, the land becomes more valuable for another use, or the municipality steps in with incentives.
Brokers and intermediaries
Is commercial real estate brokerage getting crushed?
Transaction-dependent brokers have been hit hard, while those with advisory skills are adapting. Fewer sales and refinancings mean fewer commissions, and brokers whose value was mainly listing and marketing assets have struggled. Brokers who help owners through maturities, recapitalizations, note sales, and creative financing remain busy, because distressed and complex situations still need experienced intermediaries.
Are commercial real estate debt and equity brokers really necessary?
Not for every deal, but often for complex ones. An experienced owner with lender relationships can finance a simple, stabilized property directly. Debt and equity brokers earn their fees when a deal needs a wider lender search, a layered capital stack, or terms the borrower can't negotiate alone, which is common in today's tighter market. Judge a broker by the lender and investor relationships they actually bring, not by their pitch.
Where the opportunity is
Is now a good time to allocate money to commercial real estate?
For patient investors buying at reset prices, it can be. Periods of frozen volume and forced selling have historically produced some of the best entry points, because buyers face less competition and can negotiate. The key is buying assets whose income supports the price at today's interest rates, using moderate fixed-rate leverage, and avoiding deals that rely on falling rates or quick appreciation. Timing the exact bottom is less important than paying the right price.
Where are investors who are staying in commercial real estate finding opportunity?
In distressed and overlooked situations. Common targets include loan maturities that force sales, note purchases from lenders, recapitalizations that need fresh equity, industrial and outdoor storage in growing markets, necessity retail, and properties in smaller submarkets that institutional buyers ignore. The common thread is buying from motivated sellers at prices that work with today's financing costs.
Is anyone getting multifamily development deals done?
Some developers are, but far fewer than a few years ago. Projects that move forward usually have a low land basis, public incentives, tax-exempt bond or agency financing, a market with little new supply, or a well-capitalized sponsor that can fund more equity. Many others are on hold because construction costs, interest rates, and scarce LP equity make returns too thin.
Why do some large metros have so few commercial real estate opportunities on the market?
Because owners there aren't being forced to sell yet. In some major markets, owners hold stable assets with long-term, fixed-rate debt, so listings stay scarce even when demand exists. Elsewhere, buyers avoid markets with high property taxes, weak population growth, or policy uncertainty, so capital markets activity stays thin in both directions. The opportunity often sits in off-market deals, lender-held assets, and smaller nearby submarkets.
Risks and next steps for owners
What is the risk of waiting for prices to recover before selling?
The floor may give way before your timeline does. Rescue capital propping up values accrues at 12%–18% or more ahead of common equity, loans keep maturing, and lenders are shifting from modifications to discounted debt sales at 30%–85% markdowns. When those sales set real comps, owners who waited can face lower prices, a maturity they can't refinance, or a lender that controls the outcome.
What should an owner do first if they need to sell or recapitalize in a frozen market?
Get a realistic number and a plan before a deadline forces one. Order a current valuation, subtract the loan and selling costs, and compare holding that equity with redeploying it, counting the loan maturity, capital needs and tax position such as a 1031. Then test the market quietly with qualified buyers and hire the broker who can create the most competition, even from outside your market. Talk with Carson before signing an exclusive letter of intent.
Sources
- Federal Reserve Bank of St. Louis (FRED) — 10-Year Treasury Constant Maturity Rate (DGS10) — Treasury yields referenced in the cap-rate spread discussion; source: Board of Governors of the Federal Reserve System
Primary sources for the page's material claims. Figures attributed to third parties are as reported by those sources on the dates shown; Carson's views are labeled as his opinion.
Selling or buying commercial property? Let's talk.
Brokerage and equity participation for commercial real estate owners, investors, and family offices — worldwide, through the eXp Commercial platform.
Carson Jones
Carson Jones is the host of Carson's Corner: Commercial Real Estate, author of The Red Flag Playbook, a licensed commercial real estate advisor and business broker, and the founder of Passive Investments. With 18 years of experience as an entrepreneur and 12 years specializing in passive investing, Carson works with high-net-worth individuals, family offices, business owners, and sophisticated investors as a broker and principal.
Carson holds a BBA in Finance from Baylor University and his Tennessee commercial real estate license (#382989). He actively pursues acquisition and equity opportunities across the United States and abroad through a worldwide network of qualified buyers, family offices, institutional investors, and top-tier developers.